25 past-paper questions on this unit. Five of them are below. Answer on the page: each one is marked the moment you pick, the correct option is shown whether or not you found it, and the full explanation opens either way.
CIE 0452 AccountingPaper 1 MCQsFree account
Correction of errors: five questions to try now
Real past-paper questions, the answer key from the mark scheme, and the explanation that goes with it. No account needed to answer them.
Question 1
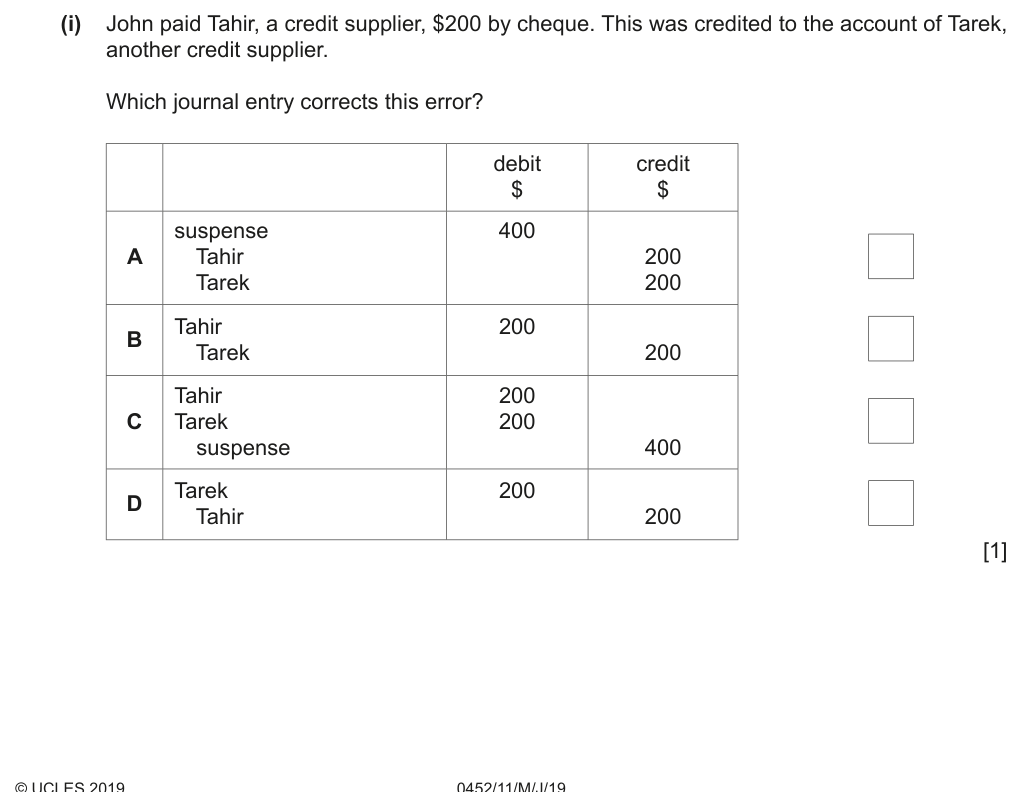
Use the complete source image for the question and answer choices. Source reference: S19 Paper 11, Q1(i).
Answer: C.
Work out what was actually posted. The correct entry was to debit Tahir 200 and credit bank 200. What happened was a credit to Tarek of 200, so the debit to Tahir was never made and Tarek received a credit he should not have. The books are short of 400 in debits, which is why suspense holds a debit balance of that amount. The correction therefore needs two debits, 200 to put Tahir right and 200 to cancel the credit wrongly given to Tarek, with 400 credited to suspense to clear it. C is correct. A reverses every line. B credits Tarek again, doubling the original error. D corrects Tarek but then credits Tahir, leaving him further from the truth.
Question 2
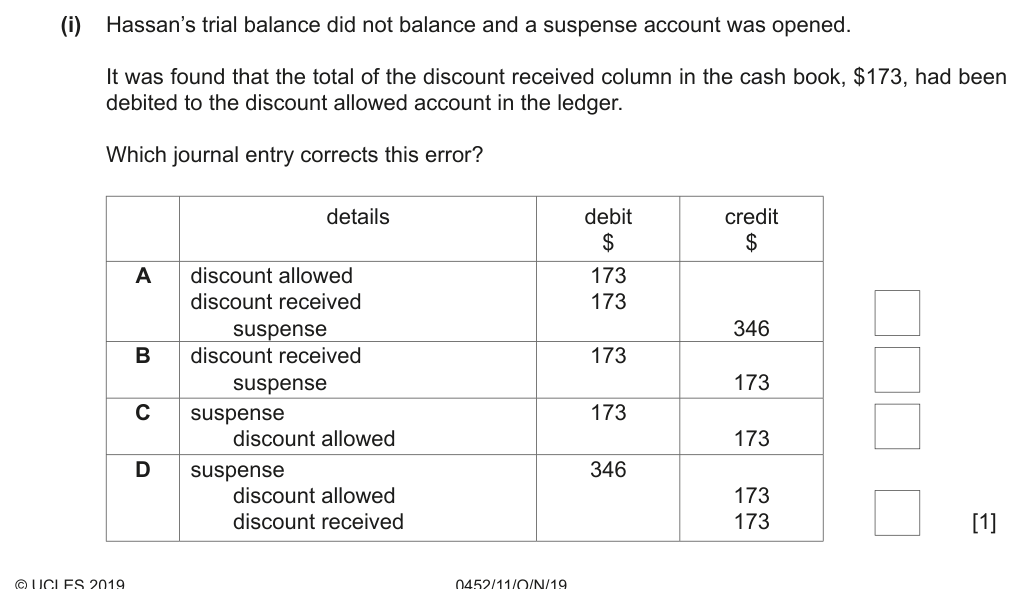
Use the complete source image for the question and answer choices. Source reference: W19 Paper 11, Q1(i).
Answer: D.
Discount received is income and should have been CREDITED to the discount received account. Instead it was debited to discount allowed, so two things are wrong at once: there is a debit of 173 that should not exist, and a credit of 173 that was never made. Correcting it needs a credit of 173 to remove the wrong debit from discount allowed and a credit of 173 to put discount received right, which is 346 of credits, matched by a debit of 346 to clear the suspense account. D is correct. A reverses every line. B puts discount received on the debit side, the wrong side for income. C only removes the wrong entry and never makes the right one.
Question 3
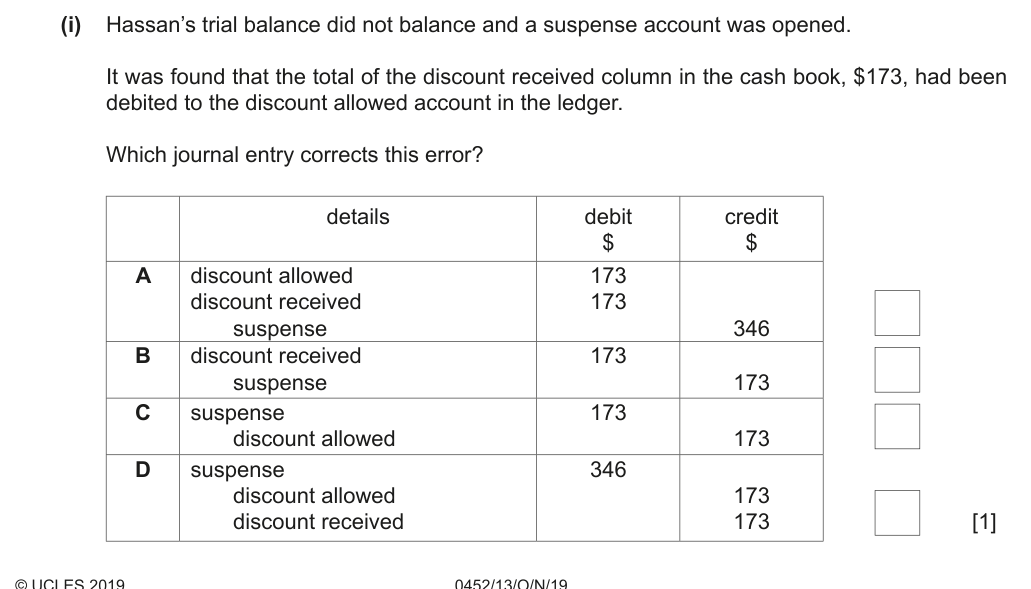
Use the complete source image for the question and answer choices. Source reference: W19 Paper 13, Q1(i).
Answer: D.
Discount received is income and should have been CREDITED to the discount received account. Instead it was debited to discount allowed, so two things are wrong at once: there is a debit of 173 that should not exist, and a credit of 173 that was never made. Correcting it needs a credit of 173 to remove the wrong debit from discount allowed and a credit of 173 to put discount received right, which is 346 of credits, matched by a debit of 346 to clear the suspense account. D is correct. A reverses every line. B puts discount received on the debit side, the wrong side for income. C only removes the wrong entry and never makes the right one.
Question 4
Davi prepared the following journal entry to correct an error. debit credit $ $ Samir 40 Samuel 40 Which error was being corrected?
Answer: D.
Read the correction backwards to find the error. The journal debits Samir and credits Samuel, so the original entry must have debited Samuel when it should have debited Samir. That is D: goods sold to Samir should put the debt on Samir's account, and it went to Samuel's instead, an error of commission between two accounts of the same class. C is the same mistake in the other direction, so its correction would be the reverse journal. A and B would each need a suspense entry as well, because in both of them a debit was replaced by a credit, which leaves the trial balance out of agreement and cannot be fixed by two personal accounts alone.
Question 5
At the end of his financial year, Zane opened a suspense account. Why was it necessary to open this account?
Answer: B.
A suspense account exists for one reason: the trial balance totals did not agree, and the difference has to be parked somewhere so that the statements can be prepared while the error is hunted down. B is correct. C is wrong because an error of commission puts the right amount on the right side in the wrong account of the same class, so the totals still agree and nothing needs parking. D reverses the purpose, since the account is opened after an error has already shown itself. A is not a real situation: suspense is created when needed, not carried in the ledger waiting to be forgotten.
These questions are drawn from past CIE 0452 Accounting papers and filtered to correction of errors. You answer, you find out immediately whether you were right, and you get the reasoning for the correct option and for each distractor. Wrong answers go to a mistakes locker so you can come back to exactly those.
Practice is free. You need an account only so your progress and your mistakes are still there next time.
These are the errors that cost marks on correction of errors, taken from our own topic notes. Read them before you practise and you will recognise the traps in the questions.
Using a suspense account to correct a two-sided error.
Correcting a reversal with the original amount instead of double it.
Adjusting profit for an error that moved figures only between two customers or two suppliers.
Getting the direction wrong: an overstated expense increases the corrected profit.
Leaving a suspense balance in the final accounts.
Forgetting to change capital after correcting the profit.
Writing "to correct the error" as the narrative instead of saying what was corrected.