Bank reconciliation: five questions to try now
Real past-paper questions, the answer key from the mark scheme, and the explanation that goes with it. No account needed to answer them.
Question 1
Which statement about a bank reconciliation statement is correct? Use the complete source image for the question and answer choices. Source reference: M19 Paper 12, Q1(e).
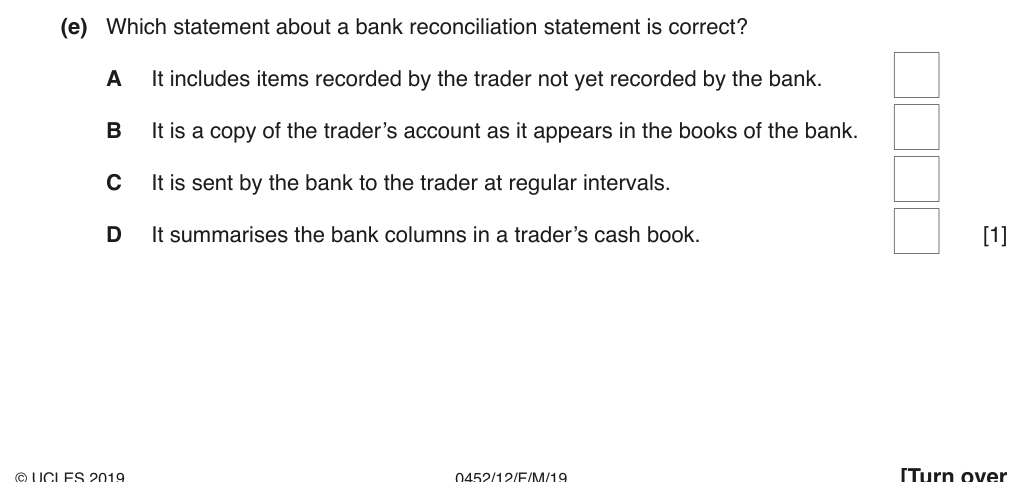
Answer: A.
Question 2
The balance of cash at bank shown in the cash book is $1200. The bank statement at the same date shows the balance to be $1440.
What could explain the difference?
Answer: C.
Question 3
Jamal’s bank statement at 1 May 2021 showed a bank overdraft of $1460.
At that date there were unpresented cheques of $385 and uncredited deposits of $255.
What was the cash book balance on 1 May 2021?
Answer: C.
Question 4
Jamal’s bank statement on 1 September 2022 showed a bank overdraft of $1460.
At that date there were unpresented cheques of $385 and uncredited deposits of $255.
What was the bank balance in the cash book on 1 September 2022?
Answer: C.
Question 5
What is true about a bank statement?
1 It is a demand by the bank for repayment of an overdraft.
2 It shows a positive bank balance as a debit balance.
3 It shows transactions affecting the bank account in a given period.
Answer: D.
What this practice covers
These questions are drawn from past CIE 0452 Accounting papers and filtered to bank reconciliation. You answer, you find out immediately whether you were right, and you get the reasoning for the correct option and for each distractor. Wrong answers go to a mistakes locker so you can come back to exactly those.
Practice is free. You need an account only so your progress and your mistakes are still there next time.
What examiners see students get wrong here
These are the errors that cost marks on bank reconciliation, taken from our own topic notes. Read them before you practise and you will recognise the traps in the questions.
- Putting bank charges or standing orders in the reconciliation statement instead of the cash book.
- Reversing the treatment of unpresented cheques and outstanding lodgements.
- Using the original cash book balance in the reconciliation rather than the corrected one.
- Forgetting to reinstate the customer's debt when a cheque is dishonoured.
- Getting the sign wrong on an overdraft.
- Showing the bank statement balance in the statement of financial position instead of the corrected cash book balance.
Revise it first
If any of the above is unfamiliar, work through the notes before practising: Bank reconciliation revision notes.