Disposal and revaluation: five questions to try now
Real past-paper questions, the answer key from the mark scheme, and the explanation that goes with it. No account needed to answer them.
Question 1
How were the vehicle disposal and replacement recorded in the provision for depreciation account? Use the complete source image for the figures and answer choices.
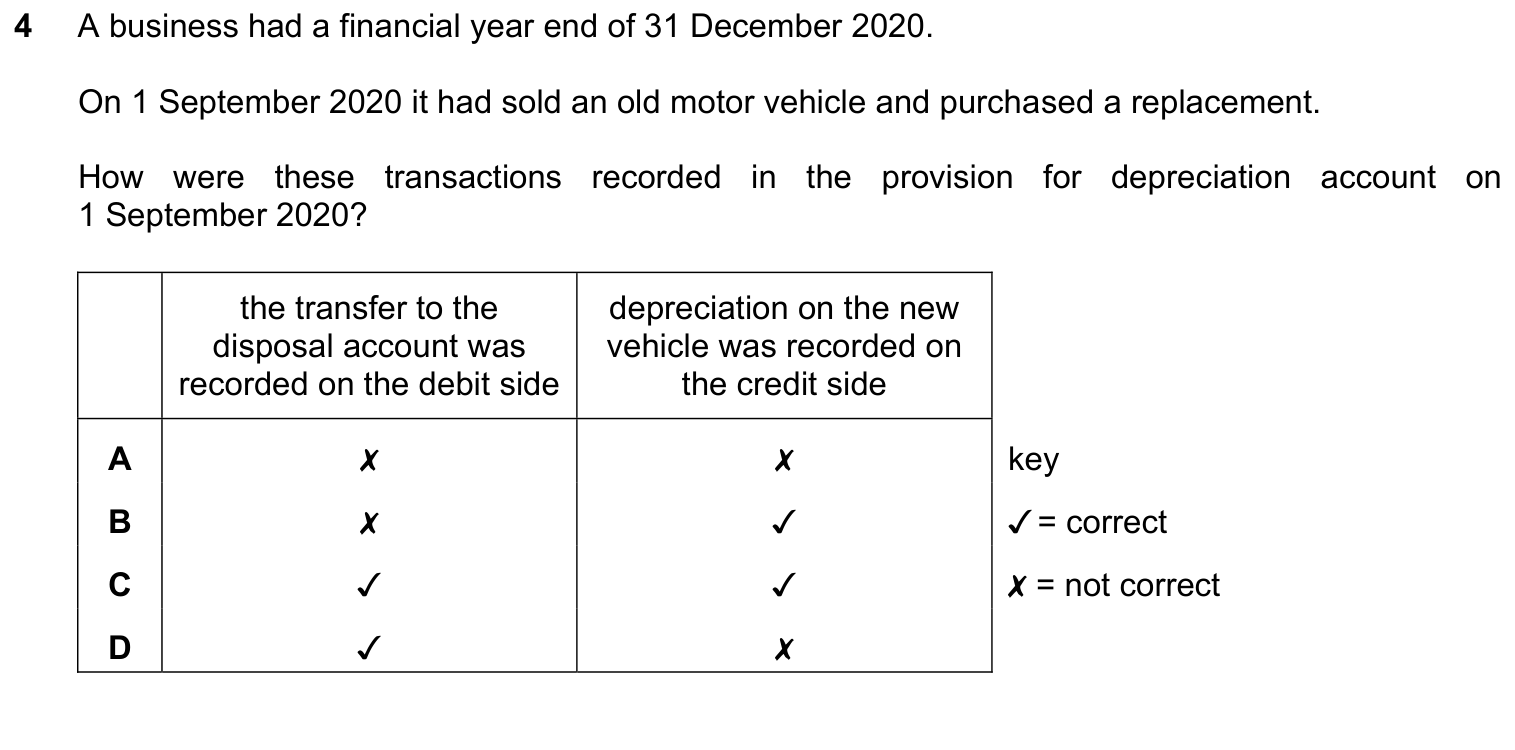
Answer: D.
Question 2
Jason sold a non-current asset with a carrying value of $8000. He mistakenly recorded this by debiting the bank account and crediting the sales account with the proceeds of $6500.
By which amount was the profit for the year overstated?
Answer: D.
Question 3
A company revalued its premises upwards.
Which statement about the increase in value is correct?
Answer: A.
Question 4
A business purchased a vehicle which had cost $27 000 and had an estimated residual value of $1000. Depreciation of $18 200 has been charged on this vehicle.
The vehicle was sold in part exchange for a new vehicle which cost $29 500. A cheque for $19 000 was paid in settlement of the transaction.
Which profit or loss was made on the sale of the vehicle?
Answer: C.
Question 5
The following information is available. $ freehold premises at cost 125 000 provision for depreciation of freehold premises 50 000 The premises were revalued at $180 000. Which entries are required to record the revaluation? Each answer gives, in order: income statement; freehold premises at cost account; provision for depreciation; revaluation reserve.
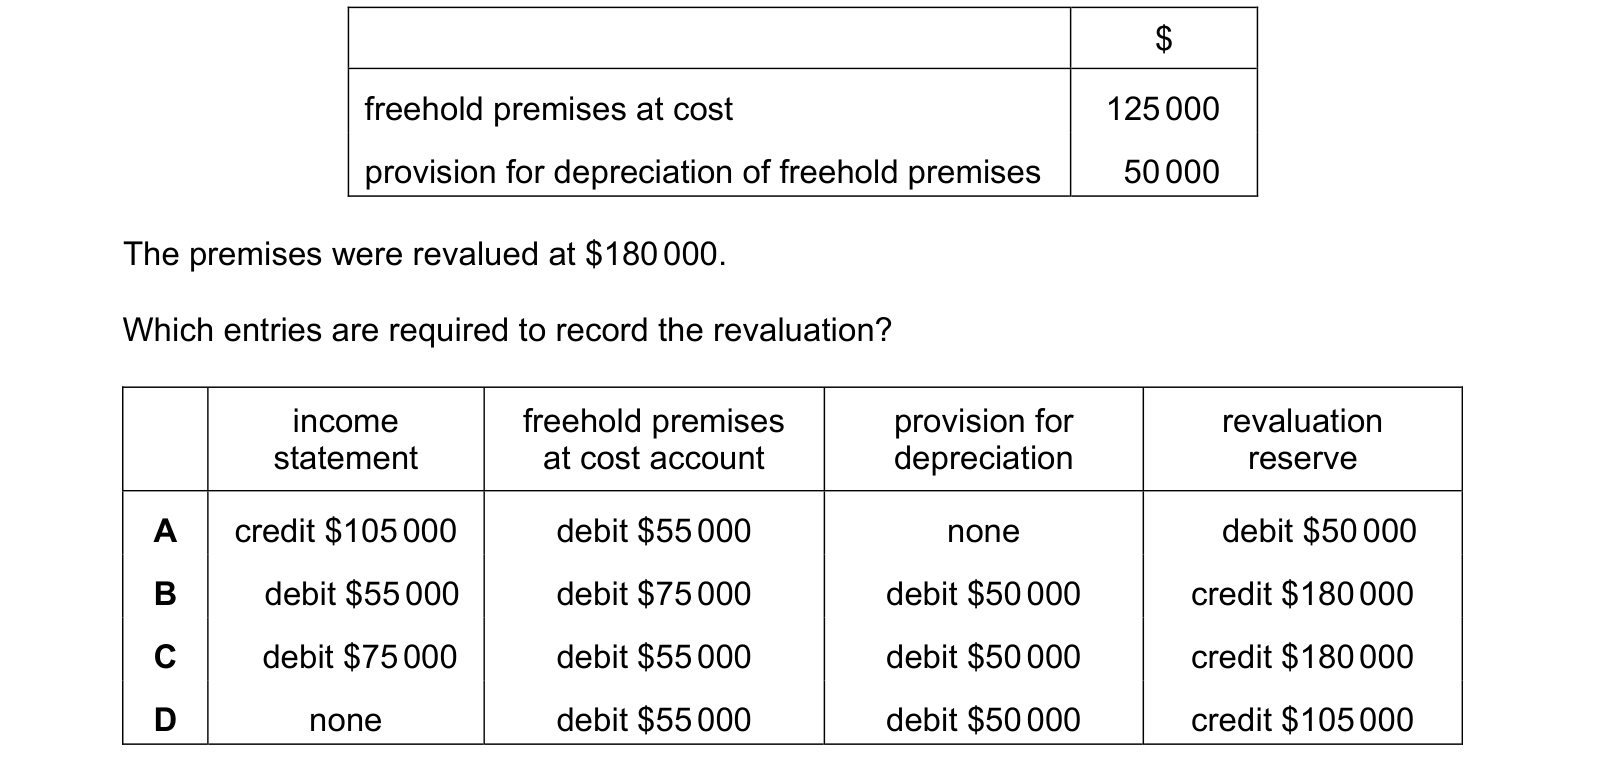
Answer: D.
What this practice covers
These questions are drawn from past CIE 9706 Accounting papers and filtered to disposal and revaluation. You answer, you find out immediately whether you were right, and you get the reasoning for the correct option and for each distractor. Wrong answers go to a mistakes locker so you can come back to exactly those.
Practice is free. You need an account only so your progress and your mistakes are still there next time.
What examiners see students get wrong here
These are the errors that cost marks on disposal and revaluation, taken from our own topic notes. Read them before you practise and you will recognise the traps in the questions.
- Forgetting to transfer the accumulated depreciation to the disposal account.
- Comparing proceeds with cost instead of with carrying amount.
- Capitalising only the cash paid in a part exchange.
- Taking a revaluation surplus to the income statement.
- Paying a dividend out of the revaluation reserve.
- Continuing to depreciate on the old cost after a revaluation.
- Saying a profit on disposal means the asset was sold well, without explaining that it means depreciation was overcharged.
Revise it first
If any of the above is unfamiliar, work through the notes before practising: Disposal and revaluation revision notes.