Question 1
A company prepared its purchases ledger control account, which showed a balance of $15 960. The following items were then discovered. What was the correct total of the trade payables?
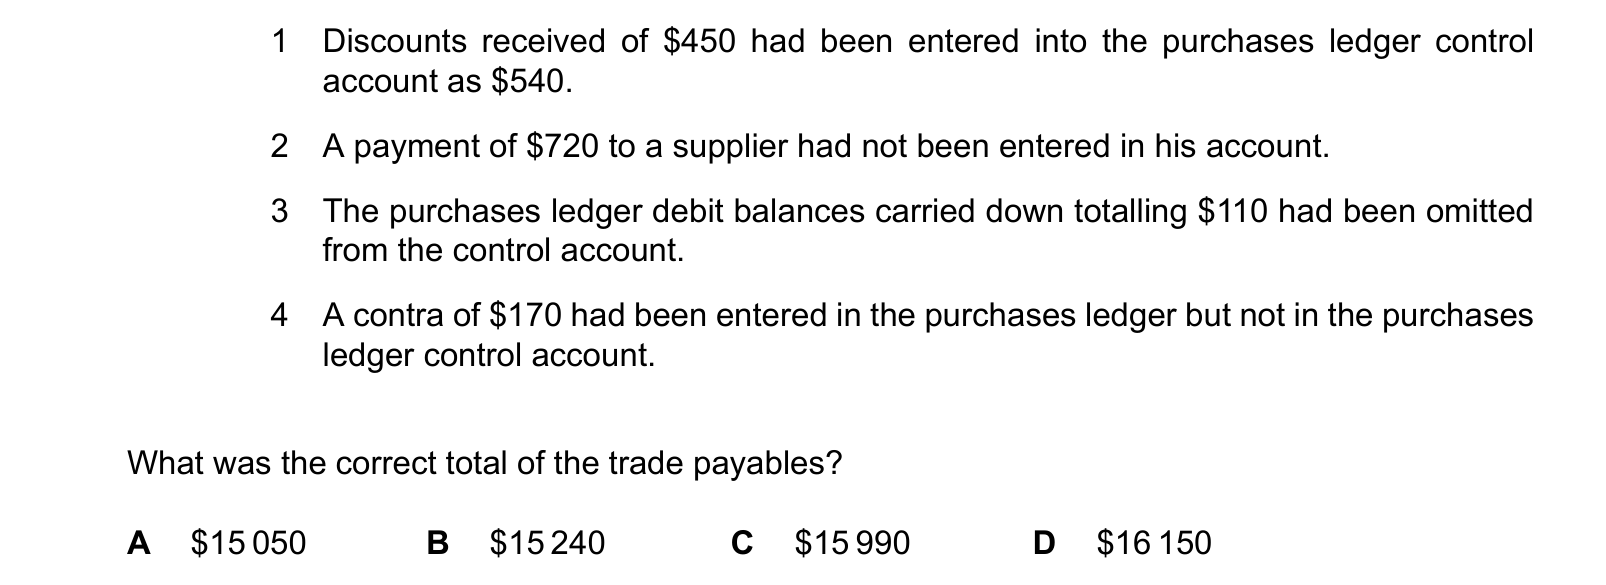
Answer: C.
Question 2
The purchases ledger control account for a business shows a closing balance of $7640.
The following items were then discovered. What was the credit balance to carry down after adjusting for these items?
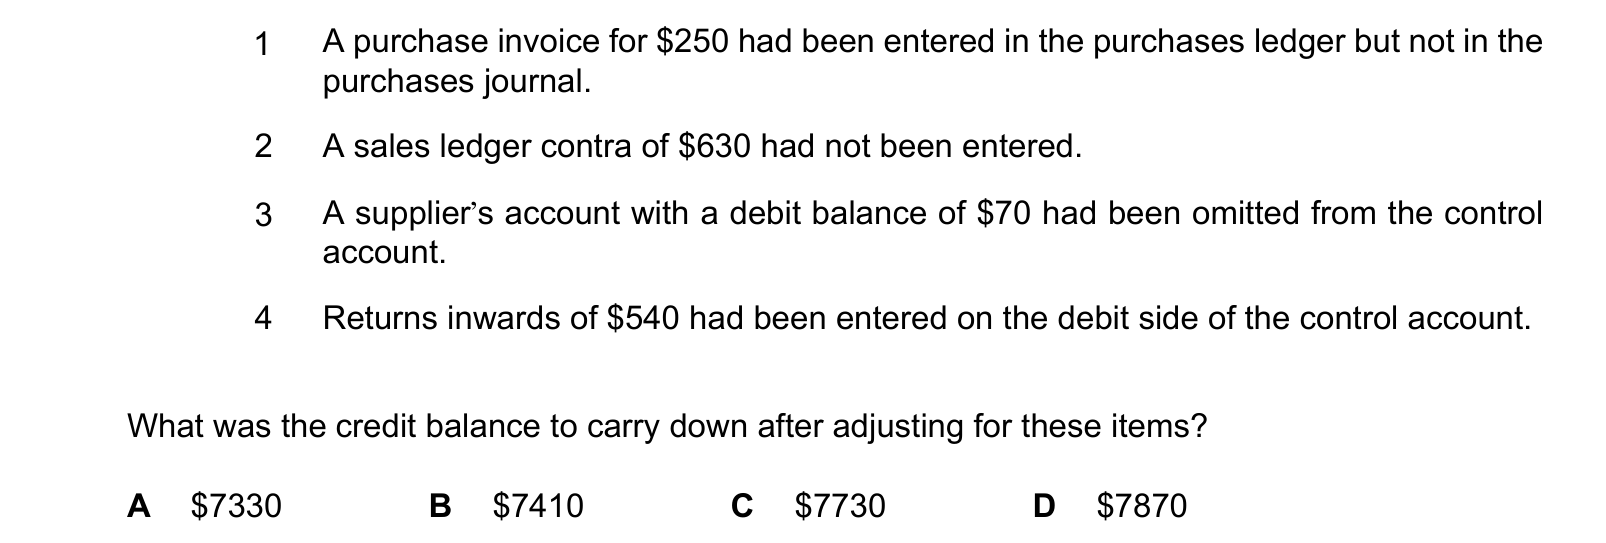
Answer: D.
Question 3
The opening balance on a purchases ledger control account was $18400. The following errors or omissions were then discovered. What was the corrected balance on the purchases ledger control account?
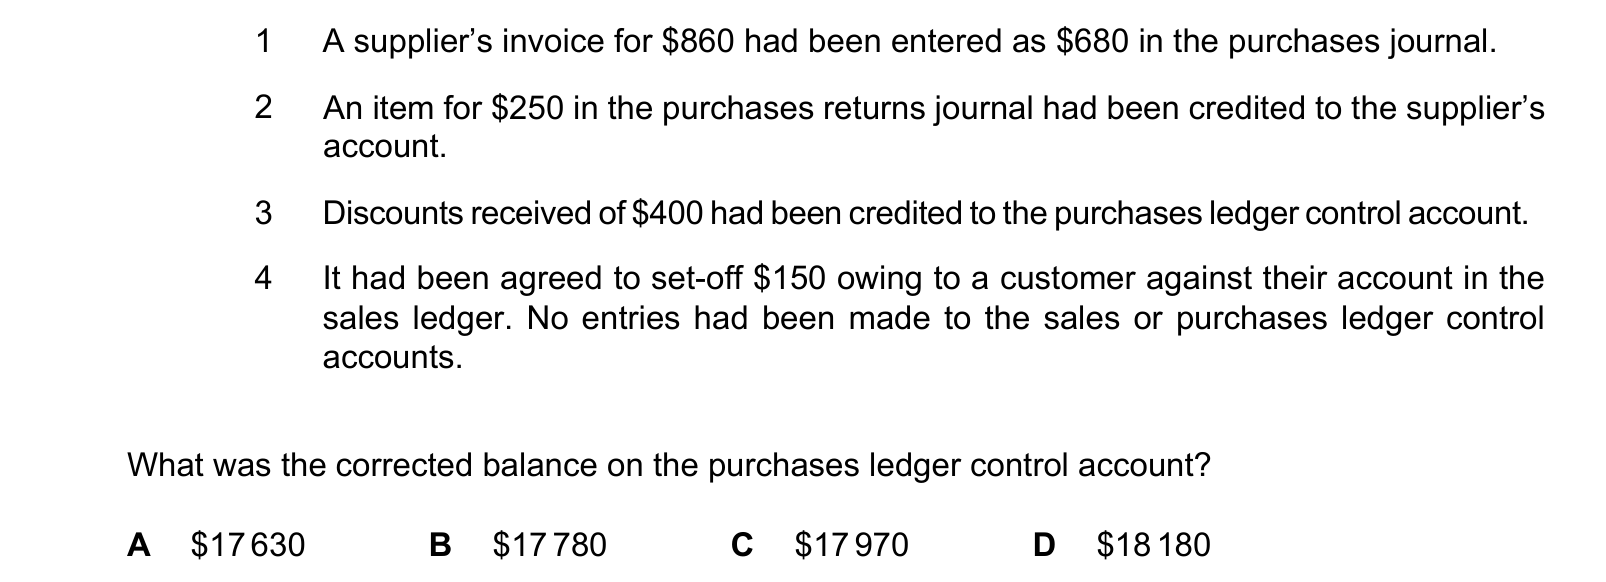
Answer: A.
Question 4
Where is discount allowed recorded? Each answer gives, in order: cash book; discount allowed account; sales ledger control account.
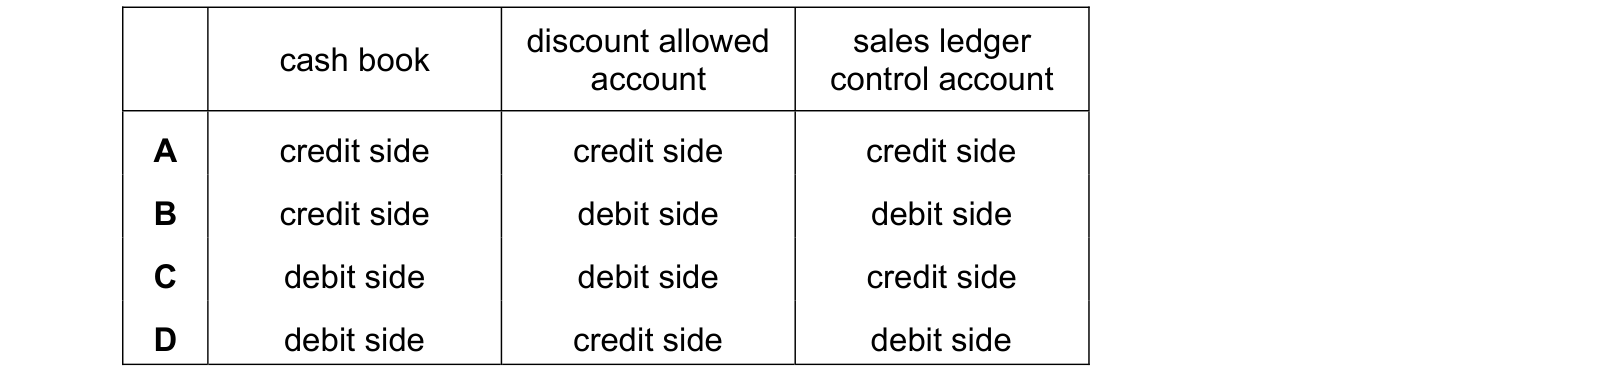
Answer: C.
Question 5
A sales invoice to Jane has not been recorded in the books of prime entry. Which accounts are affected by this error? Each answer gives, in order: sales ledger control; Jane.
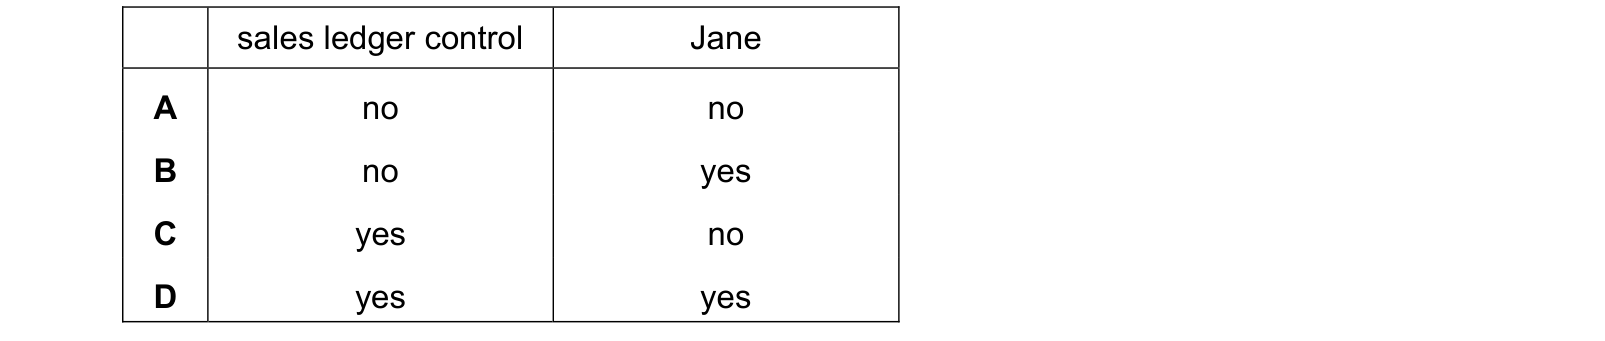
Answer: D.
What this practice covers
Real past-paper questions, the answer key from the mark scheme, and the explanation that goes with it. Each one is marked the moment you pick, the correct option is shown whether or not you found it, and the full explanation opens either way. No account needed to answer them.
These questions are drawn from past CIE 9706 Accounting papers and filtered to control accounts. You answer, you find out immediately whether you were right, and you get the reasoning for the correct option and for each distractor. Wrong answers go to a mistakes locker so you can come back to exactly those.
Practice is free. You need an account only so your progress and your mistakes are still there next time.
What examiners see students get wrong here
These are the errors that cost marks on control accounts, taken from our own topic notes. Read them before you practise and you will recognise the traps in the questions.
- Including cash sales or cash purchases.
- Putting discount allowed on the debit side of the sales ledger control account.
- Including the allowance for irrecoverable debts.
- Putting the contra on the wrong side, or contra'ing more than the smaller balance.
- Treating the sales ledger control account as a credit balance.
- Saying an agreeing control account proves the ledger is correct.
- Forgetting that a dishonoured cheque is a debit in the sales ledger control account, restoring the amount the customer owes.
Revise it first
If any of the above is unfamiliar, work through the notes before practising: Control accounts revision notes.