Absorption costing: five questions to try now
Real past-paper questions, the answer key from the mark scheme, and the explanation that goes with it. No account needed to answer them.
Question 1
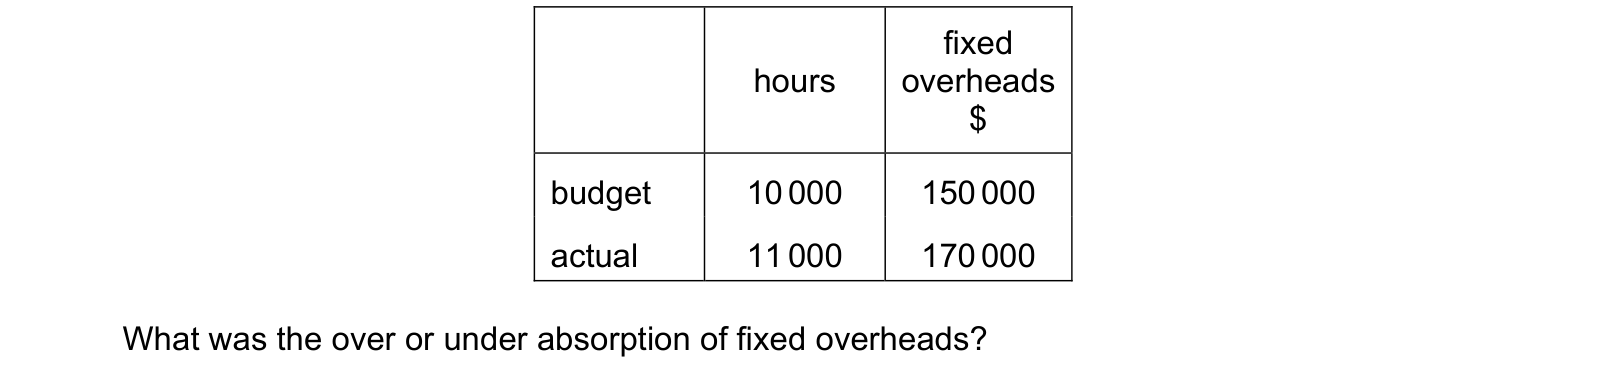
A company’s fixed overheads details were as shown.
fixed hours overheads $ budget 10 000 150 000
actual 11 000 170 000
What was the over or under absorption of fixed overheads?
Answer: B.
Question 2
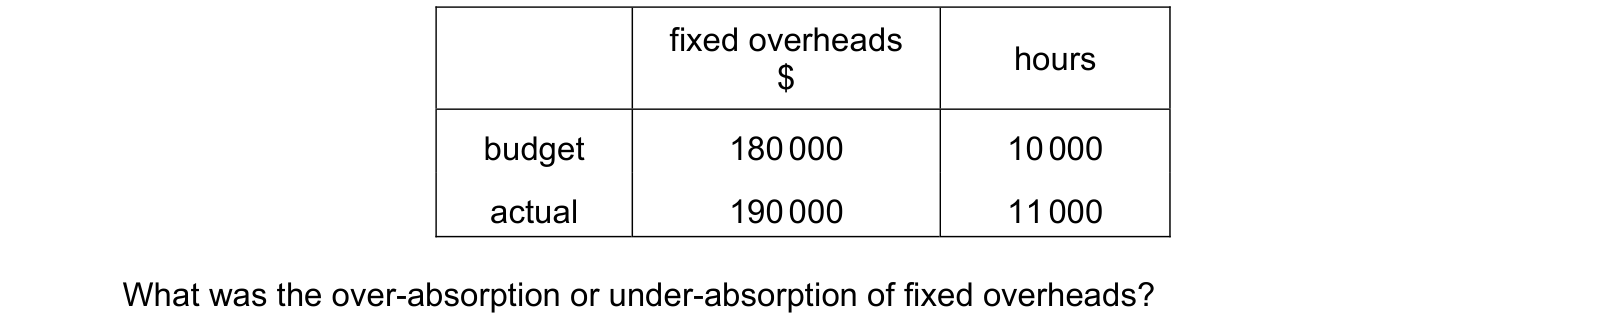
The following information is available for a business.
fixed overheads hours $ budget 180 000 10 000
actual 190 000 11 000
What was the over-absorption or under-absorption of fixed overheads?
Answer: A.
Question 3
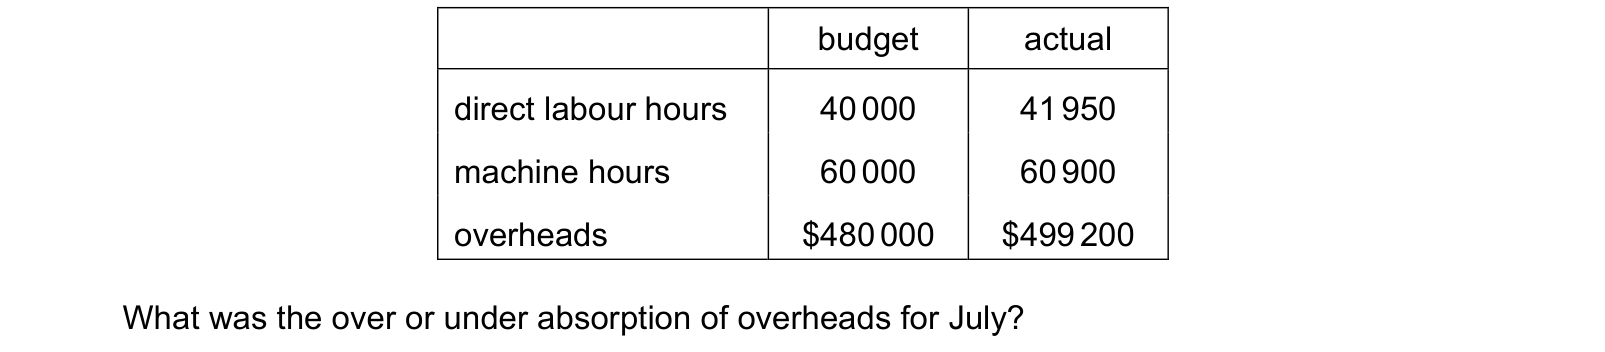
The following data were available for a department for July.
budget actual
direct labour hours 40 000 41 950
machine hours 60 000 60 900
overheads $480 000 $499 200
What was the over or under absorption of overheads for July?
Answer: D.
Question 4
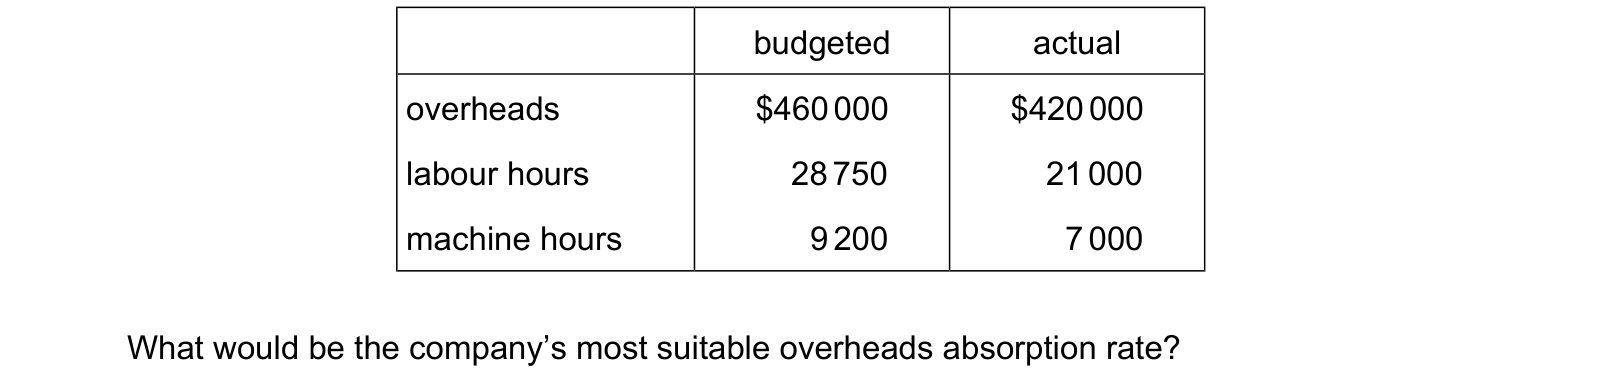
The following budgeted and actual information is available.
budgeted actual
overheads $460000 $420000
labour hours 28750 21000
machine hours 9200 7000
What would be the company’s most suitable overheads absorption rate?
Answer: A.
Question 5
A manufacturing business has a service department, X, and production departments, Y and Z. Department Z is labour intensive. How is the overhead absorption rate set for department Z? Each answer gives, in order: first task; second task; third task.
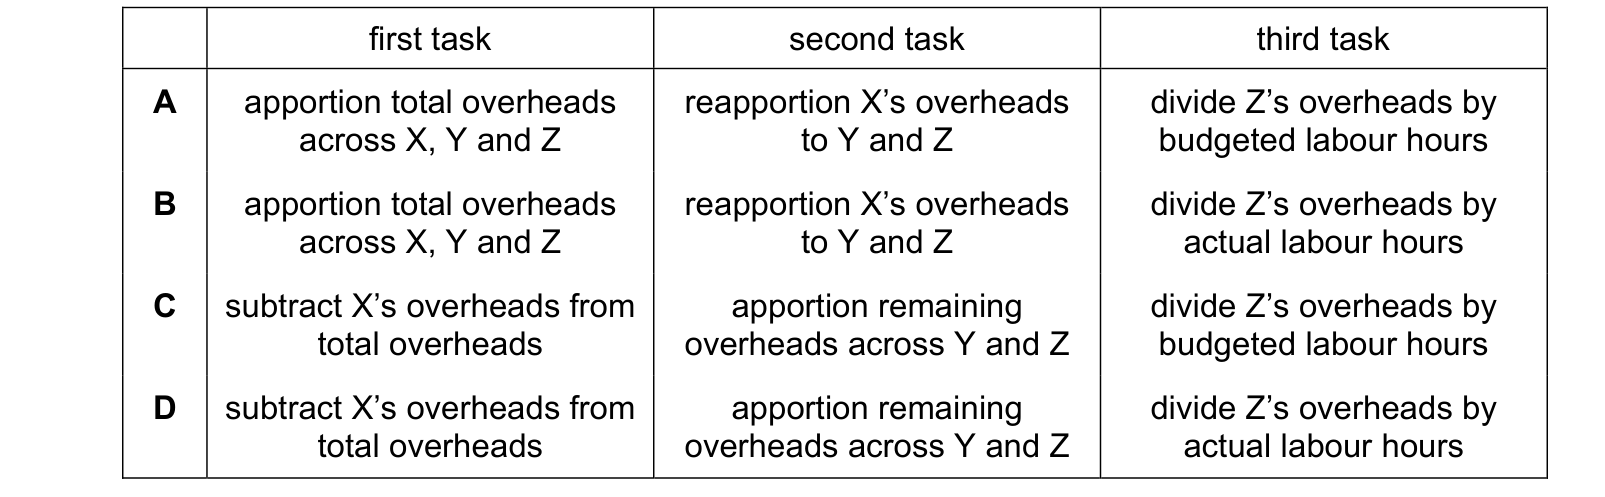
Answer: A.
What this practice covers
These questions are drawn from past CIE 9706 Accounting papers and filtered to absorption costing. You answer, you find out immediately whether you were right, and you get the reasoning for the correct option and for each distractor. Wrong answers go to a mistakes locker so you can come back to exactly those.
Practice is free. You need an account only so your progress and your mistakes are still there next time.
What examiners see students get wrong here
These are the errors that cost marks on absorption costing, taken from our own topic notes. Read them before you practise and you will recognise the traps in the questions.
- Using the words allocation and apportionment as though they meant the same thing.
- Recalculating the absorption rate using actual figures at the year end.
- Using budgeted activity instead of actual activity to calculate overhead absorbed.
- Getting the direction wrong: under-absorption reduces profit.
- Absorbing service department costs directly onto products without reapportioning first.
- Apportioning on a basis with no link to the cost, such as splitting rent by number of machines.
- Including selling and administration overheads in the absorption rate. Only production overheads are absorbed.
Revise it first
If any of the above is unfamiliar, work through the notes before practising: Absorption costing revision notes.