43 past-paper questions on this unit. Five of them are below. Answer on the page: each one is marked the moment you pick, the correct option is shown whether or not you found it, and the full explanation opens either way.
CIE 0452 AccountingPaper 1 MCQsFree account
Partnerships: five questions to try now
Real past-paper questions, the answer key from the mark scheme, and the explanation that goes with it. No account needed to answer them.
Question 1
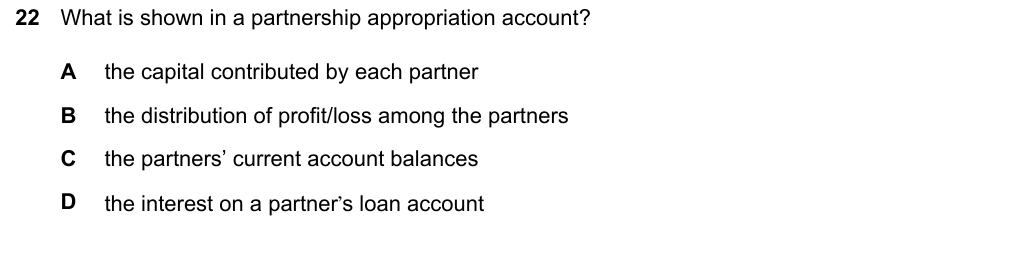
What is shown in a partnership appropriation account? Use the complete source image for the question and answer choices. Source reference: S24 Paper 11, Q22.
Answer: B.
The appropriation account takes the profit the income statement has already calculated and shows how it is divided between the partners. B is correct. A names capital, which is recorded in the capital accounts and changes only when a partner puts money in or takes it out. C names the current account balances, which are the RESULT of the appropriations rather than part of them. D is the trap: interest on a partner's LOAN is a cost of borrowing charged before the profit is struck, so it never reaches the appropriation account.
Question 2
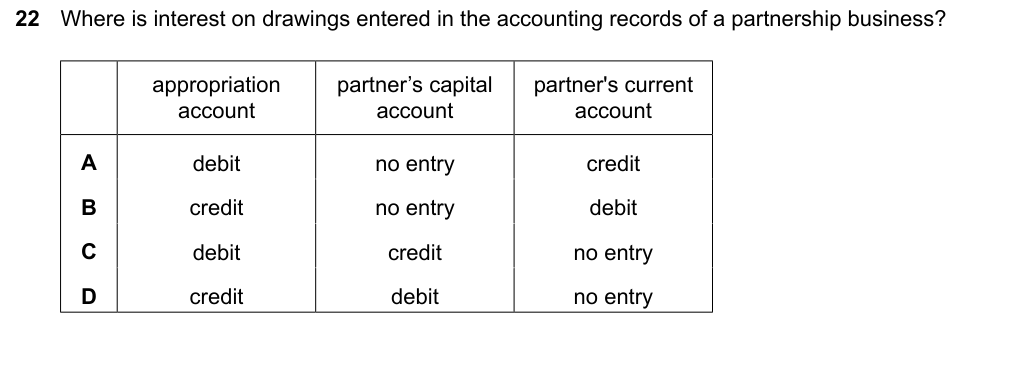
Where is interest on drawings entered in the accounting records of a partnership business? Use the complete source image for the question and answer choices. Source reference: S24 Paper 12, Q22.
Answer: B.
Interest on drawings is charged to the partner for taking money out during the year, so it does two things. It goes back into the pool of profit available for sharing, which means CREDITING the appropriation account, and it reduces what that partner is entitled to, which means DEBITING his current account. The capital account is untouched, since capital moves only when capital itself is introduced or withdrawn. B is correct. A reverses both entries, and C and D use the capital account instead of the current one.
Question 3
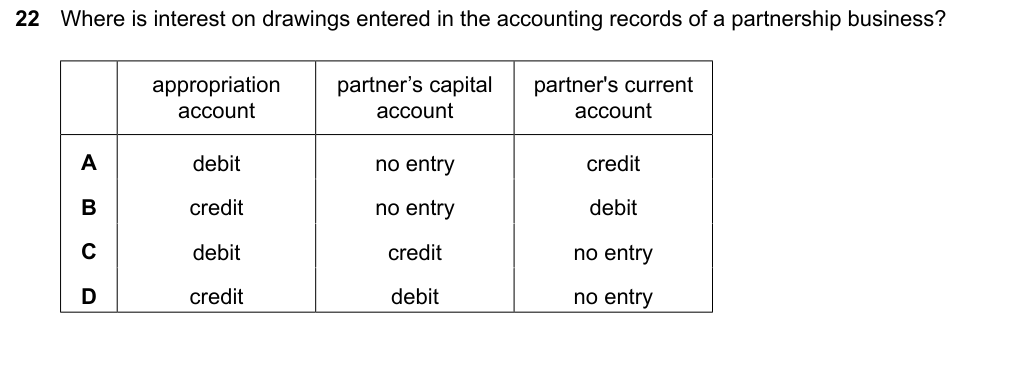
Where is interest on drawings entered in the accounting records of a partnership business? Use the complete source image for the question and answer choices. Source reference: S24 Paper 13, Q22.
Answer: B.
Interest on drawings is charged to the partner for taking money out during the year, so it does two things. It goes back into the pool of profit available for sharing, which means CREDITING the appropriation account, and it reduces what that partner is entitled to, which means DEBITING his current account. The capital account is untouched, since capital moves only when capital itself is introduced or withdrawn. B is correct. A reverses both entries, and C and D use the capital account instead of the current one.
Question 4
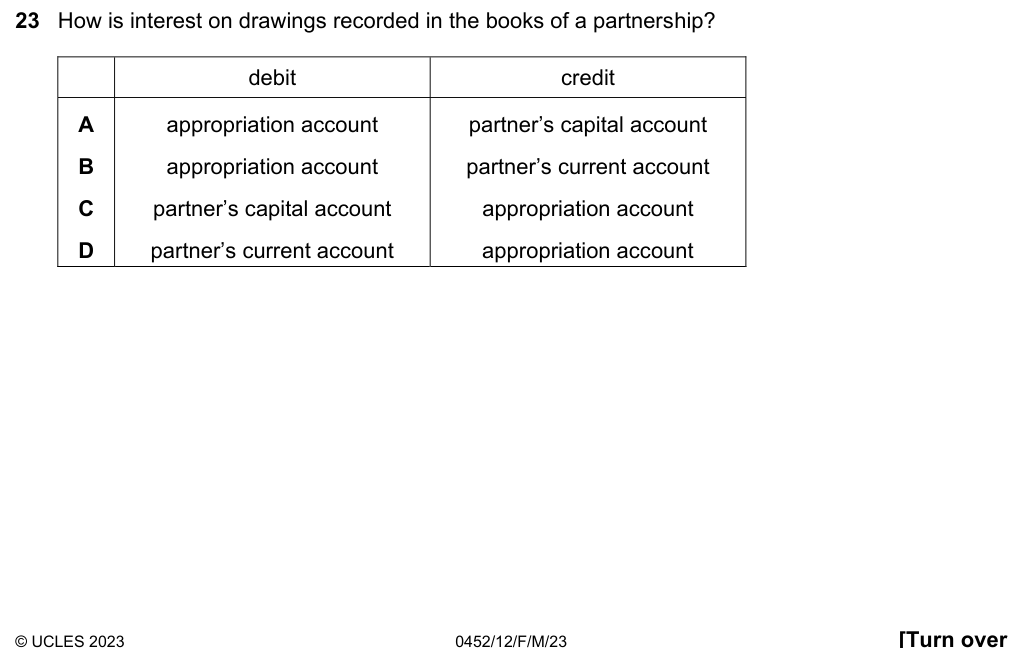
How is interest on drawings recorded in the books of a partnership? Use the complete source image for the question and answer choices. Source reference: M23 Paper 12, Q23.
Answer: D.
Interest on drawings is charged to the partner for taking money out during the year, so it reduces what he is entitled to and is DEBITED to his current account rather than his capital account. The other half is a credit to the appropriation account, because the interest goes back into the pool of profit available for sharing. D is correct. B reverses both halves. A and C use the capital account, which changes only when capital itself is introduced or withdrawn.
Question 5
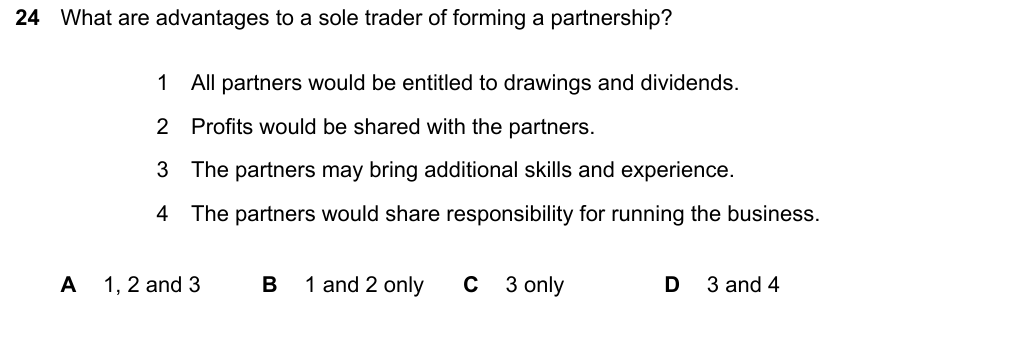
What are advantages to a sole trader of forming a partnership? Use the complete source image for the question and answer choices. Source reference: M24 Paper 12, Q24.
Answer: D.
Statements 3 and 4 are the genuine advantages: a partner may bring skills the sole trader lacks, and the responsibility for running the business is shared. D is correct. Statement 2 is a DISADVANTAGE, since profit that one person kept entirely must now be divided. Statement 1 is simply wrong: partners take drawings, but dividends are paid by a limited company to its shareholders, and a partnership has neither shares nor shareholders.
These questions are drawn from past CIE 0452 Accounting papers and filtered to partnerships. You answer, you find out immediately whether you were right, and you get the reasoning for the correct option and for each distractor. Wrong answers go to a mistakes locker so you can come back to exactly those.
Practice is free. You need an account only so your progress and your mistakes are still there next time.
These are the errors that cost marks on partnerships, taken from our own topic notes. Read them before you practise and you will recognise the traps in the questions.
Treating a partner's salary or interest on capital as an expense in the income statement.
Deducting interest on drawings instead of adding it.
Sharing the profit in the ratio of the capital balances when a profit-sharing ratio is given.
Applying the Partnership Act defaults when there is an agreement, or forgetting them when there is not.
Sharing the whole profit before deducting salaries and interest on capital.
Putting a debit balance on a current account among current assets.
Charging interest on a partner's loan in the appropriation account. It is an expense.