38 past-paper questions on this unit. Five of them are below. Answer on the page: each one is marked the moment you pick, the correct option is shown whether or not you found it, and the full explanation opens either way.
CIE 0452 AccountingPaper 1 MCQsFree account
Clubs and societies: five questions to try now
Real past-paper questions, the answer key from the mark scheme, and the explanation that goes with it. No account needed to answer them.
Question 1
Which accounting statement prepared by the treasurer of a sports club provides a summary of all the monies received and paid out during the financial year?
Answer: C.
A receipts and payments account is a summary of the club's cash book, listing every sum received and every sum paid during the year, so it is the statement the question describes and C is correct. B, the income and expenditure account, matches income to the period it belongs to and includes non-cash items such as depreciation, so it is not a summary of money moved. D shows a position at one date rather than a year's movements. A explains the difference between the cash book and the bank statement, which is a different job again.
Question 2
Which group contains only items which may be recorded in both the income statement of a trading business and the income and expenditure account of a club?
Answer: A.
Bank charges, depreciation and wages are ordinary running costs that any organisation incurs, so all three appear in a trading business's income statement and in a club's income and expenditure account alike. A is correct. B fails on gross profit and sales revenue: a club shows the PROFIT from a trading activity such as a shop as a single line of income rather than its sales and gross profit. C fails on deficit, which only a club reports, and C and D both include the treasurer's expenses, an office that exists only in a club.
Question 3
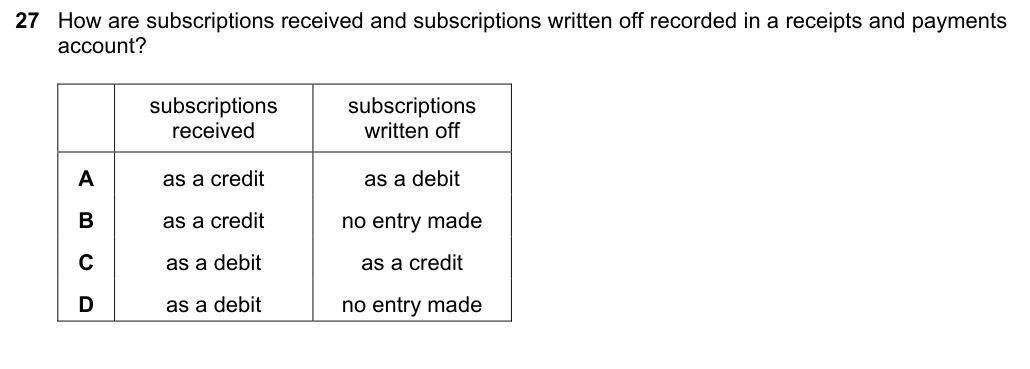
How are subscriptions received and subscriptions written off recorded in a receipts and payments account? Use the complete source image for the question and answer choices. Source reference: W23 Paper 11, Q27.
Answer: D.
A receipts and payments account is a summary of the cash book, so money coming in is a DEBIT, exactly as in the cash book itself. Subscriptions written off are amounts the club has given up hope of collecting, and no money moves, so nothing is entered at all. D is correct. A and B place receipts on the credit side, which reverses the convention. A and C make an entry for the write off, but a record of cash cannot hold a transaction in which no cash appeared.
Question 4
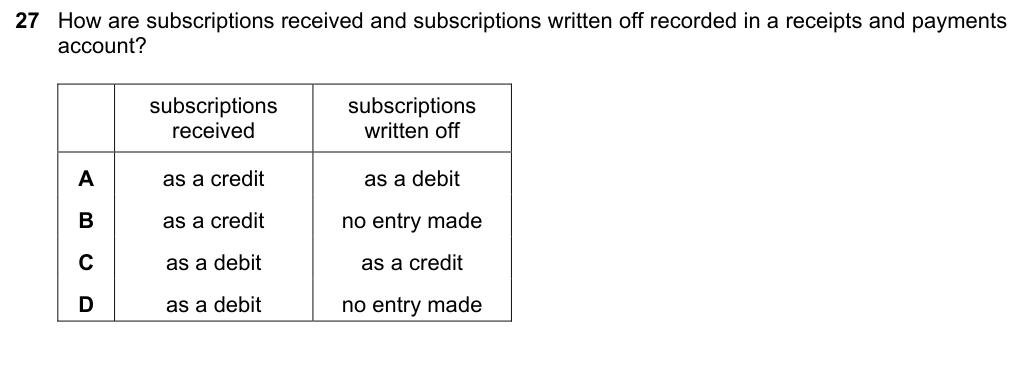
How are subscriptions received and subscriptions written off recorded in a receipts and payments account? Use the complete source image for the question and answer choices. Source reference: W23 Paper 13, Q27.
Answer: D.
A receipts and payments account is a summary of the cash book, so money coming in is a DEBIT, exactly as in the cash book itself. Subscriptions written off are amounts the club has given up hope of collecting, and no money moves, so nothing is entered at all. D is correct. A and B place receipts on the credit side, which reverses the convention. A and C make an entry for the write off, but a record of cash cannot hold a transaction in which no cash appeared.
Question 5
A sports club operates a shop selling running shoes to members. These shoes are purchased on credit terms from suppliers. Which item is recorded in the receipts and payments account?
Answer: B.
A receipts and payments account records money in and money out, nothing else, so of the four only the payments to suppliers qualify. B is correct. A, the inventory of shoes, is a valuation of goods held at the year end. C, purchases of shoes, is the wrong item even though it sounds like cash, because the shoes are bought on CREDIT, so the purchase and the payment happen at different times and only the payment involves money moving. D is a calculated result rather than a transaction.
These questions are drawn from past CIE 0452 Accounting papers and filtered to clubs and societies. You answer, you find out immediately whether you were right, and you get the reasoning for the correct option and for each distractor. Wrong answers go to a mistakes locker so you can come back to exactly those.
Practice is free. You need an account only so your progress and your mistakes are still there next time.
These are the errors that cost marks on clubs and societies, taken from our own topic notes. Read them before you practise and you will recognise the traps in the questions.
Including the purchase of equipment in the income and expenditure account.
Including depreciation in the receipts and payments account.
Treating subscriptions in advance as an asset.
Using the cash received as the subscriptions income without adjusting.
Putting bar takings, rather than bar profit, into the income and expenditure account.
Calling the result a profit instead of a surplus.
Forgetting to calculate the opening accumulated fund when the question needs it.