Economic Growth: five questions to try now
Real past-paper questions, the answer key from the mark scheme, and the explanation that goes with it. No account needed to answer them.
Question 1
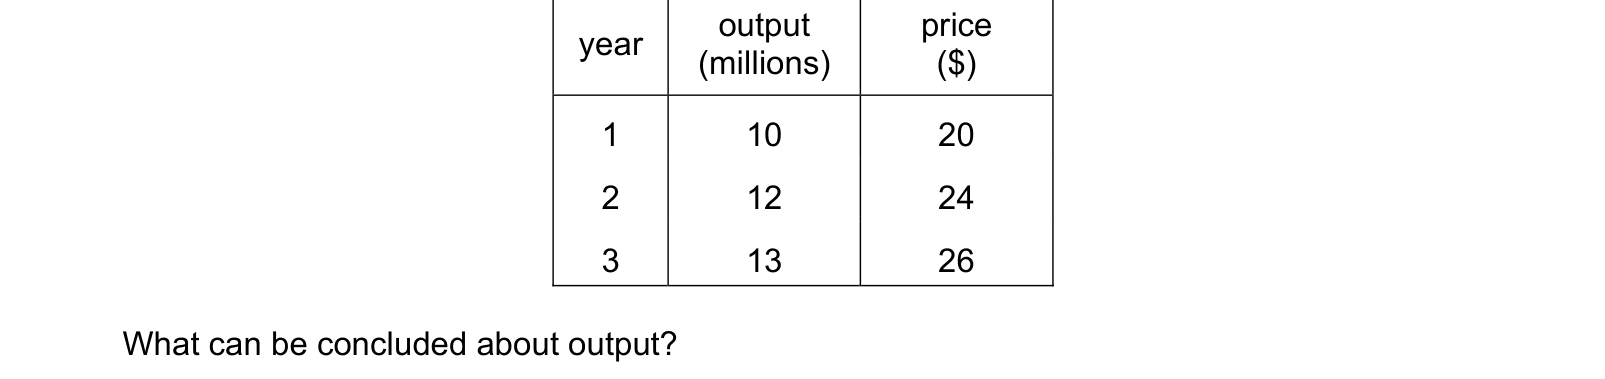
The table shows a country’s total output and its average price in each of three years. year output (millions) price ($) 1 10 20 2 12 24 3 13 26 What can be concluded about output?
Answer: B.
Explanation:
- Nominal output refers to the total value of goods and services produced, without adjusting for inflation.
- Real output refers to the total value of goods and services produced, adjusted for inflation.
- To calculate real output, we need to take into account the changes in prices over time, which is done by adjusting the nominal output for inflation.
- Year 1: 10
- Year 2: 12
- Year 3: 13
- Year 1: $20
- Year 2: $24
- Year 3: $26
- Real output for Year 1: $20 x 10 = $200 million
- Real output for Year 2: $20 x 12 = $240 million
- Real output for Year 3: $20 x 13 = $260 million
Question 2
A teenager received a cheque for $50 as a birthday gift from her parents. The teenager paid the cheque into her savings account at the bank. Why is this gift a transfer payment?
Answer: D.
Question 3
Which items have to be added to and subtracted from Gross Domestic Product at market prices to calculate the value of Gross Domestic Product at basic prices?
Answer: D.
Market prices are what buyers actually pay, so they include taxes on products and are reduced by subsidies. Basic prices are what producers actually receive per unit. To move from one to the other, strip out the tax the government takes, subtract expenditure taxes, and add back the subsidy the producer received. The result measures output at the value accruing to producers rather than the value paid by purchasers.
Why the other options are wrong:
- A and B involve capital consumption, which is the adjustment from a gross measure to a net one. Depreciation has nothing to do with the price basis on which output is valued.
- A and C involve net property income from abroad, which is the adjustment from a domestic measure (GDP) to a national one (GNI). Again a different dimension entirely.
Question 4
A country’s net national income (NNI) is less than its gross national income (GNI).
What does this mean?
Answer: D.
Net national income is gross national income minus capital consumption: the depreciation of the existing capital stock through wear and obsolescence. Since NNI = GNI – depreciation, NNI is below GNI whenever capital has depreciated during the period, which it always does. The net measure is the more meaningful one for living standards, because it shows what the economy earned after setting aside what is needed to maintain its productive capacity.
Why the other options are wrong:
- A describes the gap between GDP and GNI, not between GNI and NNI. Net income from abroad is the adjustment that turns a domestic measure into a national one; it has already been made by the time GNI is reached.
- B suggests NNI is inflation-adjusted while GNI is not. The gross/net distinction concerns depreciation of capital, not prices. Adjusting for inflation is what converts a nominal figure into a real one, which is a separate operation applying equally to both.
- C concerns exports, which affect the level of national income but have nothing to do with the difference between the gross and net measures.
Question 5
Which is likely to cause a decrease in the public’s desired ratio of cash to bank deposits?
Answer: B.
What this practice covers
These questions are drawn from past CIE 9708 papers and filtered to economic growth. You answer, you find out immediately whether you were right, and you get the reasoning for the correct option and for each distractor. Wrong answers go to a mistakes locker so you can come back to exactly those.
Practice is free. You need an account only so your progress and your mistakes are still there next time.
What examiners see students get wrong here
These are the errors that cost marks on economic growth, taken from our own topic notes. Read them before you practise and you will recognise the traps in the questions.
- Defining growth using nominal GDP.
- Confusing an increase in the price level with an increase in output.
- Dividing by the new value rather than the original value in a growth-rate calculation.
- Assuming total GDP growth automatically raises GDP per capita.
- Claiming that all growth reduces unemployment.
- Claiming that growth always causes inflation.
- Treating an outward PPC shift and movement from inside to the PPC as identical.
- Assuming higher GDP guarantees higher welfare.
Revise it first
If any of the above is unfamiliar, work through the notes before practising: Economic Growth revision notes.