Sources of finance
Contents: 8 sections
Two ways of dividing the same list
Questions usually ask for one of these two classifications, so it pays to know both.
By duration
- Short term, under a year: bank overdraft, trade payables, factoring of receivables.
- Medium term, one to five years: bank loan, hire purchase, leasing.
- Long term, over five years: mortgage, debentures, share issue, retained earnings.
By origin
- Internal, generated by the business: retained earnings, sale of surplus non-current assets, tighter working-capital management.
- External, from outside: shares, debentures, loans, overdrafts, trade credit, grants.
The principle behind every recommendation is matching: finance a long-lived asset with long-term finance and a short-lived need with short-term finance. Buying a factory on an overdraft is the standard wrong answer, because the overdraft is repayable on demand while the factory earns over decades.
Equity
Ordinary shares carry the ownership of the company.
- Dividends are variable and paid only if the directors declare them.
- Ordinary shareholders vote, so issuing more of them dilutes existing control.
- On a winding up they are paid last, which is why they carry the most risk and the highest expected return.
Preference shares sit between equity and debt.
- A fixed percentage dividend, paid before the ordinary dividend.
- Usually no vote.
- Paid before ordinary shareholders on a winding up, and after all creditors.
- Cumulative preference shares carry forward any missed dividend to a later year; non-cumulative ones do not.
A share premium arises when shares are issued above their nominal value. It is a capital reserve: it cannot be paid out as a dividend.
A bonus issue turns reserves into share capital and raises no cash. A rights issue offers new shares to existing shareholders, usually below market price, and does raise cash. Confusing the two is common and they have opposite effects on the bank balance.
Debt
Debentures are long-term loans, usually secured on the company's assets.
- Interest is a fixed obligation, paid whether or not the company profits.
- Debenture interest is an expense in the income statement, so it reduces profit and reduces the tax charge.
- Debenture holders are creditors, not owners. They do not vote.
- They are repaid before all shareholders on a winding up.
Bank loans behave similarly, at a smaller scale and usually for a shorter term.
Dividends and interest are not the same kind of thing
This distinction carries marks across the whole syllabus.
| Debenture and loan interest | Dividends | |
|---|---|---|
| Paid to | Lenders | Owners |
| Obligation | Contractual, must be paid | Discretionary |
| In the accounts | Expense, reduces profit | Appropriation of profit |
| If there is no profit | Still payable | Not paid |
So a company that funds expansion with debentures has committed to an outflow whatever happens; one that funds it with shares has not.
Gearing
Gearing measures how much of the long-term finance is debt:
gearing = non-current liabilities / (non-current liabilities + equity) x 100
High gearing means high fixed interest commitments, so profits and risk both amplify: a good year is very good for the ordinary shareholders and a bad year can be fatal. Low gearing is safer and dilutes returns.
Choosing, and saying why
An answer that lists sources scores little. An answer that picks one and justifies it against the situation scores well. Weigh:
- Purpose and life of what is being financed, and match the term.
- Cost: interest, issue costs, the dividend expected.
- Control: will an ordinary share issue dilute the existing owners?
- Risk and existing gearing: an already highly geared company should think hard before more debt.
- Security available: a lender wants an asset to secure against.
- Legal form: a sole trader cannot issue shares at all, which rules several options out immediately.
That last point is the one most often missed. Check what the business is before recommending how it should raise money.
Common mistakes
- Recommending a share issue to a sole trader or partnership.
- Financing a non-current asset with an overdraft.
- Treating dividends as an expense, or debenture interest as an appropriation.
- Saying debenture holders own part of the company or can vote.
- Saying a bonus issue raises cash.
- Listing sources without recommending one, when the question asks for advice.
- Forgetting that a share premium cannot be distributed as a dividend.
Check you have it
Question 1
Which source of finance would be available to a public limited company but not to a partnership?
Answer: B.
Question 2
Which statements are true of a bank overdraft?
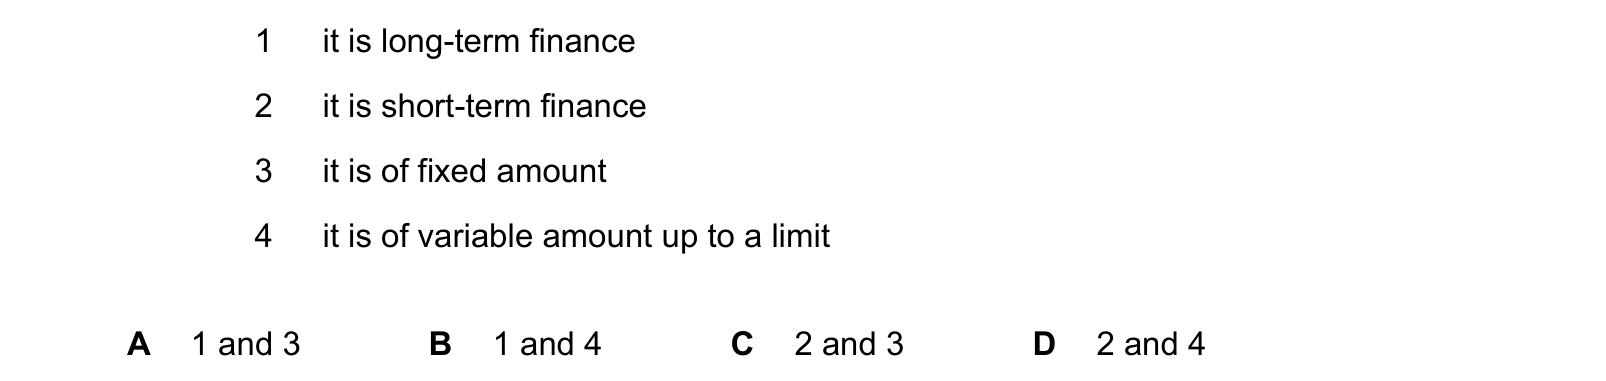
Answer: D.
What the syllabus asks for on this topicSyllabus points
Syllabus points
- Distinguish short-term, medium-term and long-term sources of finance.
- Distinguish internal from external sources.
- Explain the features of ordinary shares, preference shares, debentures and loans.
- Recommend a source of finance for a stated purpose, with reasons.
Related CIE 9706 Accounting topics
Not the topic you were looking for? Describe what you are stuck on in your own words and we will take you to the notes that answer it.